What Jersey can learn from UK fintech
Posted: 05/11/2026
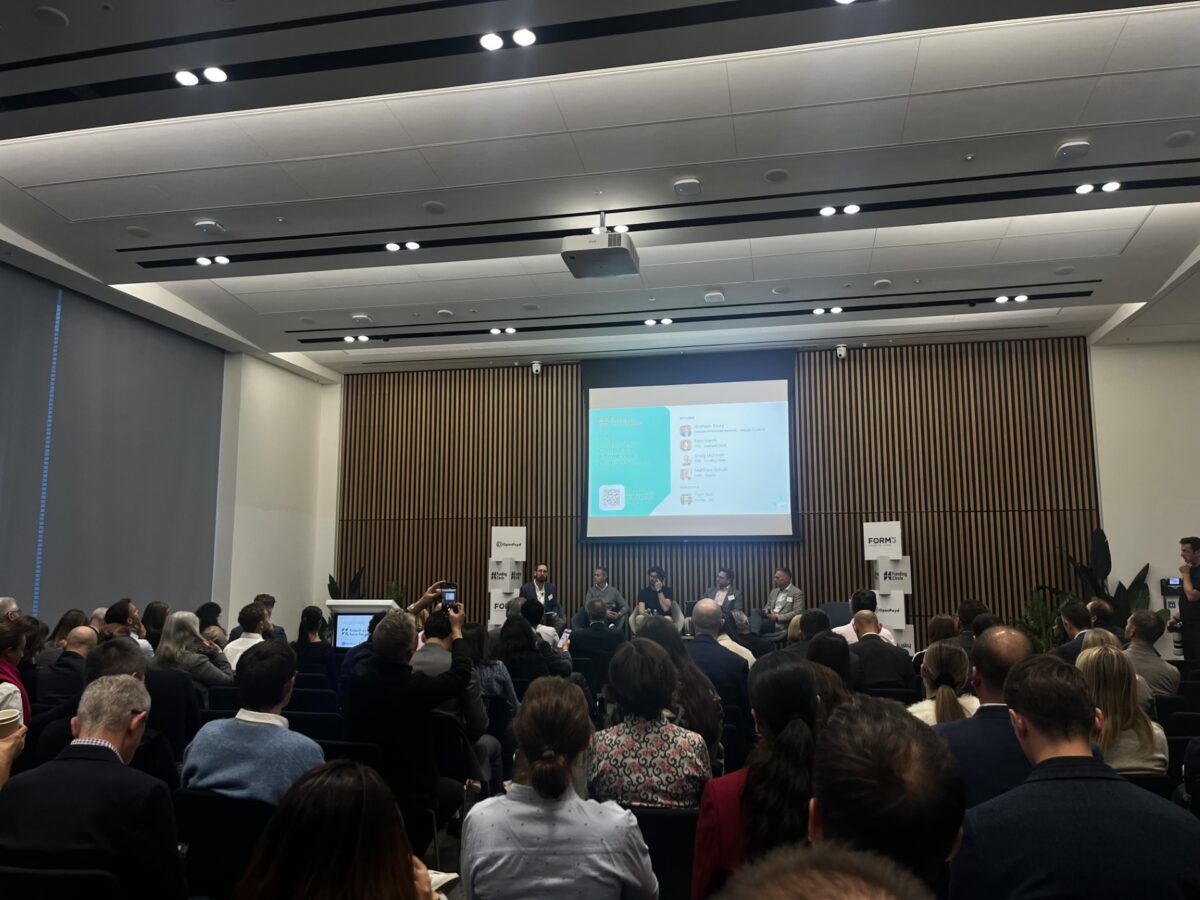
Digital Jersey’s Fintech Lead, Nathan de la Haye, attended Innovate Finance’s FinTech as a Force for Good Forum. Below, he shares a summary of his key takeaways from the event.
By Nathan de la Haye
05/11/2026
I recently attended Innovate Finance’s FinTech as a Force for Good Forum in London, hoping to learn from how the UK is promoting fintech adoption and meet some of the fintech’s leading the charge.
Payments, digital identity, AI and digital assets were recurring topics, but there was a common thread running through them: how technology can make financial services work better, while maintaining the trust and resilience the industry depends upon.
For Jersey, I think there are some useful lessons here, particularly given how much of our financial services industry involves multiple intermediaries and international clients.
TL;DR
- Fintech’s biggest opportunities may sit behind the scenes, improving the infrastructure, processes and friction within financial services rather than simply creating new customer-facing products.
- Stablecoins, tokenised deposits and programmable payments are becoming more practical, with potential applications for Jersey across funds, treasury, distributions and settlement.
- AI adoption is as much a people challenge as a technology challenge. Firms need role-specific skills for leaders, users and builders, alongside strong governance and human oversight.
- Jersey should connect fintech innovation with real industry problems, helping local financial services firms test and adopt useful technology while making the Island a more attractive place for fintech businesses to establish and grow.
- Digital Jersey can help bridge that gap through industry connections, practical knowledge-sharing, skills development and opportunities for collaboration.
Financial innovation is moving beneath the surface
One of the opening discussions explored fintech’s growing importance as part of the UK’s economic infrastructure.
Much of the attention fintech receives tends to focus on new customer-facing products, but some of the most valuable opportunities lie in improving the systems and processes operating behind the scenes.
An important distinction emerged for me: we need to understand where the friction actually comes from – implementing new technology will achieve little if the underlying barriers remain unresolved.
Some inefficiencies are technological. Others result from regulatory requirements, contractual arrangements or the way organisations have designed their processes.
Stablecoins are beginning to demonstrate practical value
One of the most interesting discussions concerned the future of money itself, particularly stablecoins, tokenised deposits and the infrastructure through which payments move.
The UK is increasingly examining these developments through the lens of financial sovereignty, including questions about sterling’s role in digital commerce and dependence on foreign-issued stablecoins.
A particularly useful example came from UK Finance’s Great British Tokenised Deposit initiative.
In September, participating banks completed live customer transactions using tokenised sterling deposits. These included remortgage completions and a marketplace purchase, where funds could be locked and automatically released when agreed conditions were met.
They provide a tangible example of how programmable payments could improve existing financial processes. I see potential applications for Jersey in areas such as fund subscriptions and redemptions, investor distributions, treasury operations and settlement.
The wider discussion about financial sovereignty also matters for Jersey. As an international finance centre operating across currencies and markets, our industry has an interest in how accessible, interoperable, and resilient future payment infrastructure becomes.
AI adoption depends on people as much as technology
AI featured prominently throughout the Forum, both in discussions about its applications in financial services and its implications for the workforce.
As firms introduce more capable systems, governance, accountability and human oversight become increasingly important.
The Financial Services Skills Commission’s May 2026 report, A Workforce Transformed, examines how AI could reshape financial services roles and the skills people will need.
If AI increasingly handles the routine tasks through which employees traditionally gain experience, firms will need to think carefully about how people develop the judgement required for more complex responsibilities.
For Jersey, this reinforces the importance of approaching AI training through specific roles and responsibilities.
Senior leaders need to understand how to identify worthwhile opportunities and assess risks. Employees using AI need the skills to challenge outputs and recognise when something is wrong. Those implementing systems require deeper technical and governance capabilities.
This was framed as a ‘leaders’, ‘users’, and ‘builders’ approach which I thought was a smart way to distinguish the training required and is consistent with the approach encouraged by the AI Playbook for Jersey.
The opportunity now is to make our training increasingly practical and relevant to the work people actually perform.
What Jersey should take from this
A final theme running through the Forum was competitiveness, including the importance of encouraging innovation and making it easier for fintech businesses to establish and grow.
For Jersey, I think there is an important connection between attracting innovative businesses and helping our existing financial services industry adopt new technology.
A fintech provider with a credible solution needs access to customers who understand the problem it solves. Financial services firms need access to appropriate technology, expertise and opportunities to explore new approaches without committing to major transformations prematurely.
This is an area where Digital Jersey can contribute by connecting businesses, sharing practical knowledge and supporting the development of relevant skills.